- Who files
- IFTA licensees based in Texas
- Due
- Last day of the month after the quarter
- Filed with
- Texas Comptroller (Webfile; paper for hardship)
- Form revisions
- 56-101 Rev. 12-16; 56-102 Rev. 1-19
- Pages
- One summary plus a supplement per fuel
At a glance
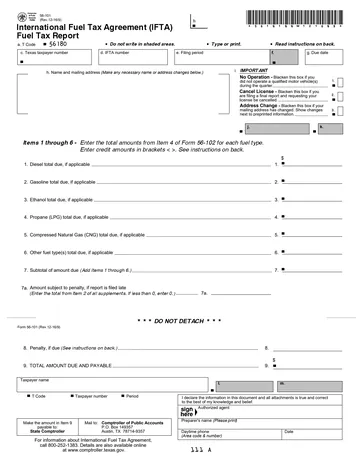
A Texas-based IFTA licensee files one quarterly report with the Texas Comptroller: the International Fuel Tax Agreement (IFTA) Fuel Tax Report, Form 56-101, with one IFTA Fuel Tax Report Supplement, Form 56-102, for each fuel type. “Each licensee holding a license under the International Fuel Tax Agreement (IFTA) is required to file, on a quarterly basis, an International Fuel Tax Agreement (IFTA) Fuel Tax Report, Form 56-101, and supplement(s), Form 56-102, with the carrier's designated base state.” This page follows Form 56-101 (Rev. 12-16/9) and Form 56-102 (Rev. 1-19/12) and the instructions on their backs. It is general information, not tax advice.
- Paper is the exception. “IFTA tax reports should be filed electronically using Webfile.” “Paper reports are accepted in case of hardship when electronic filing is not available.” Webfile asks for the same figures, so the form is still the clearest map of the return.
- Due. The last day of the month after the quarter, postmark rule, next business day after a weekend or holiday. See IFTA due dates.
- Order of work. Fill in a 56-102 for each fuel first; Form 56-101 only adds up their Item 4 totals. “Interest is calculated on Form 56-102.”
- Texas specifics. The license, decals and contacts are on the Texas IFTA page.
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
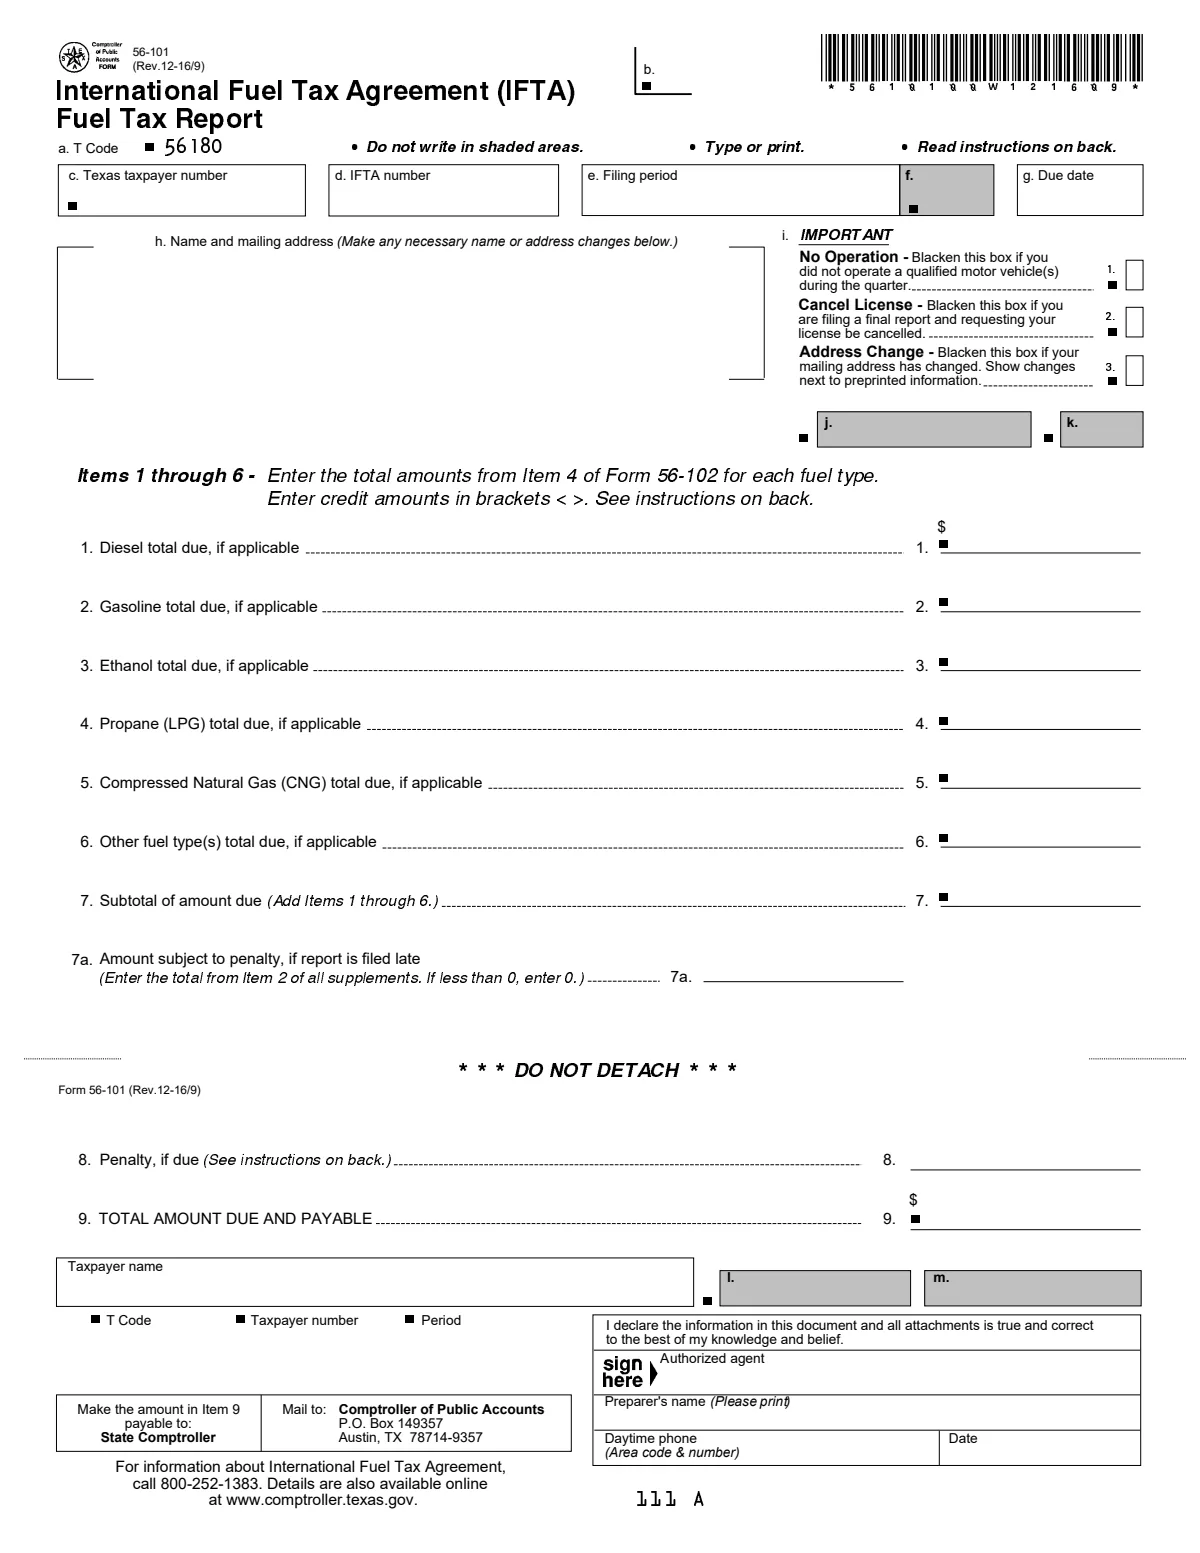
Form 56-101, line by line
| Item | Label | What goes there |
|---|---|---|
| c | c. Texas taxpayer number | Preprinted on the report the Comptroller mails you. Form 56-101 summarizes the fuel types: “Form 56-101 summarizes the tax amount of the various fuel types computed on each Form 56-102 supplement completed”. |
| d | d. IFTA number | Your Texas IFTA license number (P720.100). |
| e-g | e. Filing period, f., g. Due date | The quarter and its due date. “Reports must be postmarked no later than the last day” of the month after the quarter; a Saturday, Sunday or national holiday moves it to the next business day. Box f is for the Comptroller. |
| h | h. Name and mailing address | Preprinted from your account. Make any name or address change on the lines provided, and blacken the Address Change box. |
| i | i. Boxes 1 to 3 | 1, No Operation: you did not operate a qualified motor vehicle in the quarter (you still file). 2, Cancel License: a final report that asks for the license to be cancelled. 3, Address Change: show the changes next to the preprinted address. Leave them blank otherwise. |
| 1 | 1. Diesel total due | “Enter the total amount from Item 4 of Form 56-102 for all” diesel fuel supplements. Enter credit amounts in brackets < >. |
| 2 | 2. Gasoline total due | The Item 4 total from all gasoline supplements. |
| 3 | 3. Ethanol total due | The Item 4 total from all ethanol supplements. |
| 4 | 4. Propane (LPG) total due | The Item 4 total from all propane supplements. |
| 5 | 5. Compressed Natural Gas (CNG) total due | The Item 4 total from all CNG supplements. |
| 6 | 6. Other fuel type(s) total due | The Item 4 totals for the other fuel types the instructions list: A-55, E-85, M-85, gasohol, LNG and methanol. |
| 7 | 7. Subtotal of amount due | Add Items 1 through 6. A net credit stays in brackets. “If credit is more than $14.99, it will be automatically refunded.” |
| 7a | 7a. Amount subject to penalty | “Amount subject to penalty - Enter the sum of the total Tax” Due from Item 2 of all supplements. It leaves out interest and is needed only to figure a penalty. If less than 0, enter 0. |
| 8 | 8. Penalty | “A penalty of $50.00 or 10 percent of delinquent” taxes, whichever is greater, applies for not filing, filing late or underpaying. The worksheet on the back: multiply Item 7a by 10 percent; if that is under $50, the penalty is $50. This is the agreement's own figure: “Penalty or late filings fees ($50.00 or 10 percent of the tax, whichever is greater)” (P720.600). |
| 9 | 9. Total amount due and payable | Item 7 plus Item 8. Make the check payable to State Comptroller and mail the report to Comptroller of Public Accounts, P.O. Box 149357, Austin, TX 78714-9357 (printed on the form). |
| Sign | Declaration, authorized agent, preparer, phone, date | The signer declares the report and attachments are true and correct. Print the preparer's name and a daytime phone and date the report. The form prints no title line, which P720.800 lists as an element. |
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
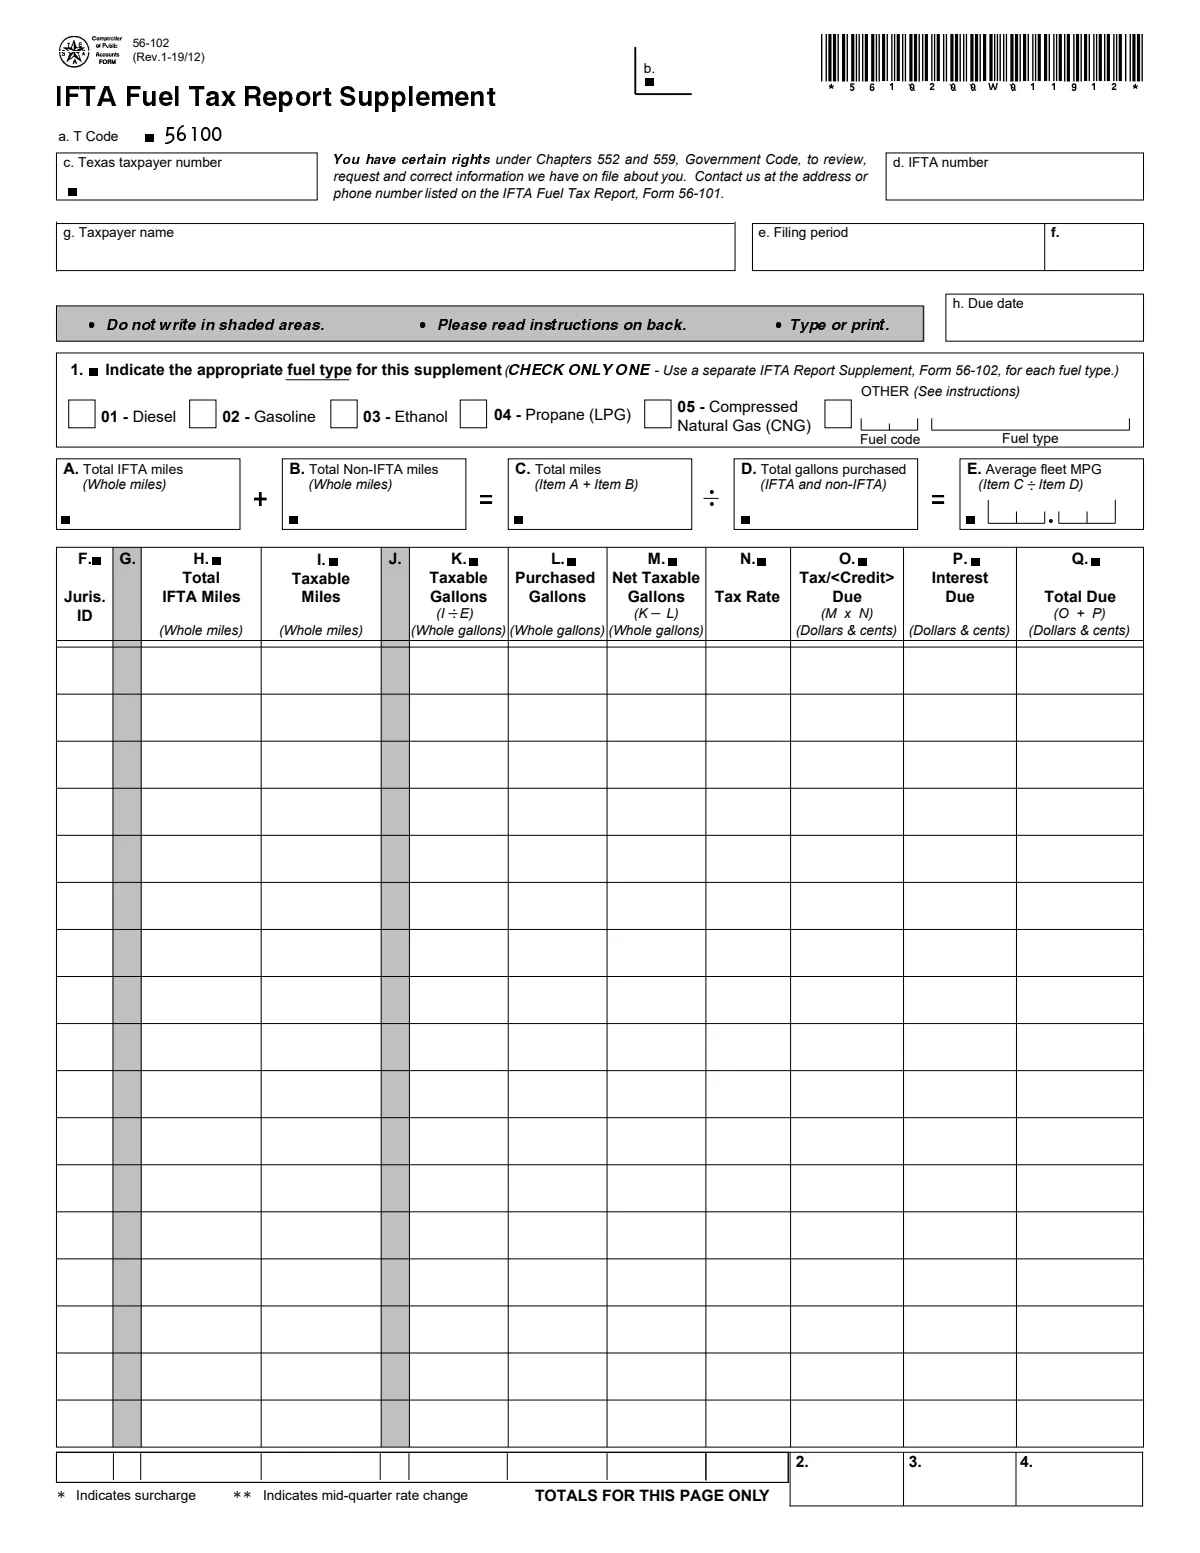
Form 56-102: fuel type and fleet MPG
The top of the supplement works out one number that drives every jurisdiction line: the fleet's average miles per gallon for this fuel.
| Item | Label | What goes there |
|---|---|---|
| S-c | c. Texas taxpayer number | The same number as on Form 56-101. |
| S-d | d. IFTA number | Your Texas IFTA license number. |
| S-g | g. Taxpayer name | As on Form 56-101. |
| S-e | e. Filing period, f. | The quarter you are reporting; f is for the Comptroller. |
| S-h | h. Due date | The due date of the quarter. |
| S-1 | 1. Fuel type | Check one box. “Use a separate Form 56-102 for each fuel type.” For OTHER, enter the two-digit fuel code and name from the back: 06 A-55, 07 E-85, 08 M-85, 09 gasohol, 10 LNG, 11 methanol, 12 biodiesel, 13 electricity, 14 hydrogen. |
| A | A. Total IFTA miles (whole miles) | “Total IFTA miles - Enter the total miles traveled in IFTA” jurisdictions by all qualified vehicles using this fuel, taxable or not. A surcharge jurisdiction's miles count once. “The total in Column H for all pages must equal item A.” |
| B | B. Total non-IFTA miles (whole miles) | Miles in the non-IFTA places the instructions name: the Northwest Territories, Yukon, Mexico, Alaska and the District of Columbia, taxable or not. |
| C | C. Total miles (Item A + Item B) | All miles of the fleet using this fuel: the P720.250 total distance. |
| D | D. Total gallons purchased (IFTA and non-IFTA) | Every gallon of this fuel put into your qualified vehicles, wherever bought, rounded to the whole gallon. “Fuel is considered "purchased" when it is pumped into your” qualified vehicle. |
| E | E. Average fleet MPG (Item C / Item D) | “Average Fleet MPG - Divide Item C by Item D. Round to 2” decimal places (P720.350). |
Form 56-102: the jurisdiction columns
One line per jurisdiction (two for a surcharge jurisdiction, more for a mid-quarter rate change). Work left to right: taxable miles become taxable gallons, the gallons you paid tax on come off, and the rest is taxed at that jurisdiction's rate.
| Column | Label | What goes there |
|---|---|---|
| F | F. Juris. ID | “Jurisdiction ID - Preprinted are all IFTA member” jurisdictions where you reported operations in the previous four quarters. Make no entries for one you did not run in; add any other by its two-letter code from the table on the back. Columns G and J are shaded: do not write in them. |
| H | H. Total IFTA miles (whole miles) | Total miles, taxable and nontaxable, in each IFTA jurisdiction for this fuel type only. Leave it blank on surcharge lines. |
| I | I. Taxable miles (whole miles) | “Taxable Miles - Enter the IFTA taxable miles for each” jurisdiction. Trip permit miles are not taxable in any jurisdiction. Miles a jurisdiction exempts (some toll roads, off-highway) are total miles but not taxable miles; see taxable miles. |
| K | K. Taxable gallons (I / E) | “Divide the amount in Column I by the” average fleet MPG in Item E: the fuel the fleet burned in that jurisdiction. |
| L | L. Purchased gallons (whole gallons) | Tax-paid gallons bought in each jurisdiction. Keep a receipt for each. From bulk storage, report only gallons put into qualified vehicles: “Fuel remaining in storage cannot” be claimed until it is used. “Column L cannot be greater” than Item D. Blank on surcharge lines. |
| M | M. Net taxable gallons (K - L) | Column K minus Column L. If K is larger, enter the taxable gallons. “If Column L is greater than Column K, enter the credit” gallons in brackets < >. |
| N | N. Tax rate | “The tax rate is listed for each preprinted IFTA” jurisdiction; otherwise take it from the rate chart. Surcharge lines (Indiana, Kentucky, Virginia) use the surcharge rate times Column K: “This surcharge is not paid at the pump or” at bulk withdrawal. A rate that changed mid-quarter means splitting the miles: “it is necessary to separate the miles traveled” during each rate period, on separate lines. |
| O | O. Tax/<Credit> Due (M x N) | Multiply Column M by Column N for each jurisdiction, in dollars and cents. A credit goes in brackets. |
| P | P. Interest due | Only for a late report: “compute interest on the tax” due for each jurisdiction, from the due date to the date the payment is postmarked, at the rate the Comptroller posts. Interest is never figured on a credit. |
| Q | Q. Total due (O + P) | Column O plus Column P for each jurisdiction. Credits in brackets. |
| S-2 | 2. Total of Column O (this page) | The page total of tax and credits. Its sum over all supplements is Item 7a on Form 56-101. |
| S-3 | 3. Total of Column P (this page) | The page total of interest. |
| S-4 | 4. Total of Column Q (this page) | “Enter the total of amounts in Column Q for all jurisdictions” on this page. Add the Item 4 totals of every supplement for a fuel type and carry the sum to that fuel's line (Items 1 to 6) on Form 56-101. |
Worked line: Item E is 6.50 MPG. Oklahoma Column I is 3,250 taxable miles, so Column K is 500 gallons. You bought 300 tax-paid gallons there (Column L), so Column M is 200 gallons. At an assumed rate of $0.19 in Column N, Column O is $38.00. The quarterly return calculator does the same arithmetic for every line; the rate here is assumed for the example, not a Texas or Oklahoma rate.
How the columns follow P720
Every member jurisdiction prints its own return, but the IFTA Procedures Manual sets what each one must hold. P720 says “Each jurisdiction shall provide, at a minimum, the following elements to be present on a standard tax return.” and P700 adds that the elements apply “regardless of the method of completion of the tax return”. The table matches the P720 list to the boxes on this form, so you can check a return line by line against the agreement.
| P720 | Element the agreement requires | Where it is on this form |
|---|---|---|
| P720.050 | Jurisdiction's name and mailing address | 56-101, bottom: Comptroller of Public Accounts, Austin |
| P720.100 and .150 | License number; licensee name and address | 56-101 boxes d and h |
| P720.200 | Tax reporting period | Box e on both forms |
| P720.250 and .300 | Total distance; total fuel | 56-102 Items C and D |
| P720.350 | Average fuel consumption factor, two decimals | 56-102 Item E |
| P720.400 | Fuel type | 56-102 Item 1 (one supplement per fuel) |
| P720.500 .010 to .050 | Rate, total miles, taxable miles, taxable volume, tax-paid volume, net taxable volume, tax, interest, total | 56-102 Columns N, H, I, K, L, M, O, P, Q |
| P720.550 | Column totals | 56-102 Items 2 to 4 |
| P720.600 and .650 | Penalty; total remittance | 56-101 Items 8 and 9 |
| P720.700 to .850 | Date, signature, title, phone | 56-101 signature block (no title line printed) |
Rules that trip people up
- One supplement per fuel type. Diesel and gasoline trucks are never mixed on one 56-102, and each fuel has its own MPG.
- Item A must equal the Column H total across all pages, and Column L can never exceed Item D.
- Surcharge lines leave Columns H and L blank and take the taxable gallons from Column K.
- Credits stay in brackets all the way to Form 56-101; a net credit over $14.99 is refunded automatically.
- File every quarter, even with no operation: blacken box i-1 and sign.
How it connects
- The method behind every column: how to file an IFTA quarterly return, step by step, and the quarterly return calculator, which runs the same P720 worksheet in your browser.
- Taxable and total miles: taxable miles vs total miles.
- Tax-paid gallons and receipts: tax-paid fuel credits and what a fuel receipt must show.
- Surcharge lines: IFTA surcharge jurisdictions.
- Dates, late filing and corrections: IFTA due dates, penalties and interest, zero returns and amended returns and refunds.
- Rates: the fuel tax rate lookup, built from the jurisdictions' own rate notices.
- Texas license, decals, bond and contacts: the Texas IFTA guide.
Questions filers ask
Can I still mail Forms 56-101 and 56-102?
Only in a hardship. The Texas Comptroller says IFTA reports should be filed electronically using Webfile and that paper reports are accepted when electronic filing is not available.
Do I need a 56-102 for every fuel?
Yes. The instructions say to use a separate Form 56-102 for each fuel type. Form 56-101 then adds up the Item 4 totals by fuel.
What goes in Column L if I fuel from my own bulk tank?
Only the gallons you pumped from bulk storage into qualified vehicles during the quarter, with tax paid. Fuel still in storage cannot be claimed until it is used.
How is the Texas late penalty figured?
On Item 7a, the tax due without interest: 10 percent of it or $50, whichever is greater. That matches the agreement's standard in Procedures Manual P720.600.
What happens to a credit on the report?
The instructions say credits are applied to current or future liability, and a credit of more than $14.99 is refunded automatically.