- Who claims
- The ultimate purchaser of the fuel
- Minimum
- $750 per claim
- When
- The quarter after the last quarter claimed
- Carrier lines
- 1a gasoline, 3a undyed diesel
- Attach to
- Form 8849
At a glance
Schedule 1 (Form 8849), Nontaxable Use of Fuels, is how the buyer of fuel gets federal fuel tax back during the year, instead of waiting for the income tax return, when the fuel went to a nontaxable use. For a motor carrier that mostly means undyed diesel burned in a reefer unit with its own motor and fuel used in off-highway business equipment. This page covers the May 2020 revision of the schedule, the one saved from irs.gov in November 2026, and only the lines a motor carrier uses: the header, line 1a and line 3a with its dye statement. The other lines are listed, not explained. It is general information, not tax advice.
- Who claims. The ultimate purchaser of the fuel.
- Minimum and timing. At least $750 per claim, filed in the quarter right after the last quarter in the claim, one claim per quarter.
- Not the truck's own fuel. “Off-highway business use doesn't include any fuel used in the propulsion motor of a registered highway vehicle even though that motor also operates special equipment by means of a power take-off or power transfer.”
- How to file. “Attach Schedule 1 to Form 8849.” Paper claims go to Department of the Treasury, Internal Revenue Service, Cincinnati, OH 45999-0002 (Form 8849 instructions).
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
The lines a carrier uses
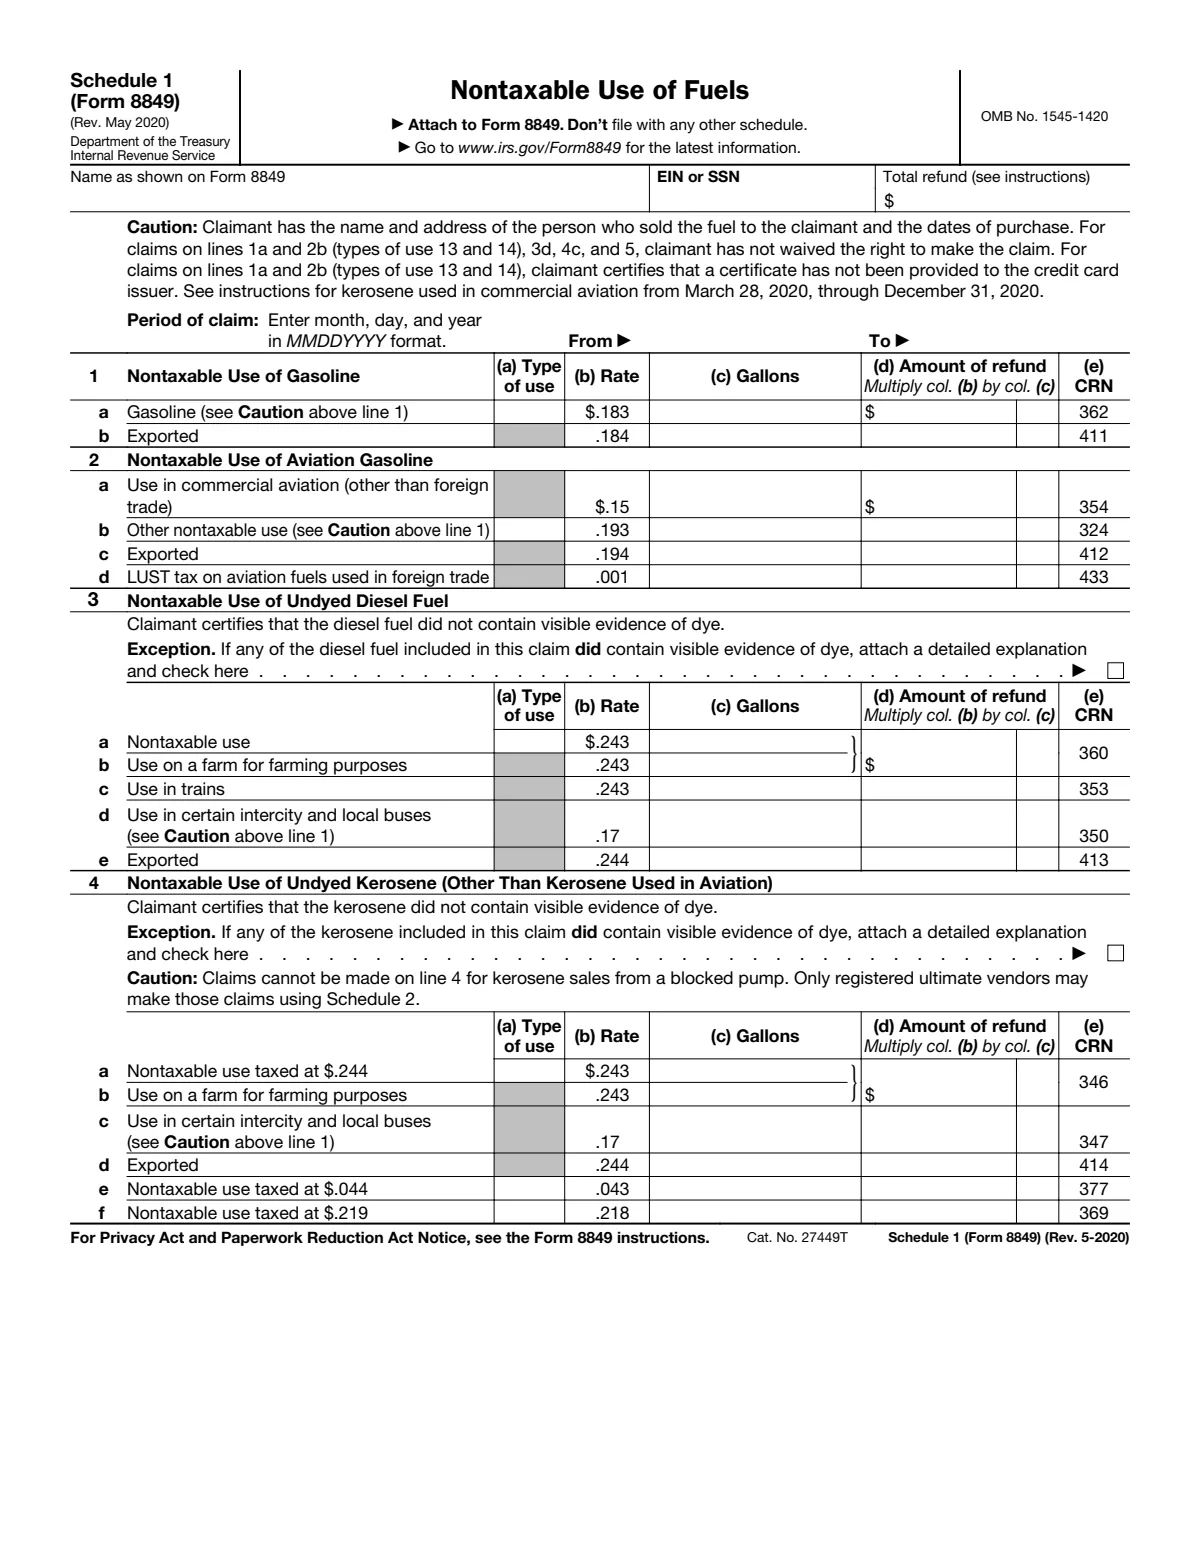
Each line asks for the type of use number from the Form 8849 instructions' table in column (a), the printed rate in column (b), gallons in column (c), and the refund (rate times gallons) in column (d). The credit reference number (CRN) is printed in column (e).
| Line | Label | What goes there |
|---|---|---|
| S1-Name | Name as shown on Form 8849 | The claimant: “An ultimate purchaser of certain fuels uses Schedule 1 to make a claim for refund.” For reefer or off-highway fuel, that is the carrier that bought the fuel and used it. |
| S1-EIN | EIN or SSN | The number on your Form 8849. The Form 8849 instructions say to enter the EIN, or the SSN if you are not required to have an EIN. |
| S1-Total | Total refund (see instructions) | “Add all amounts in column (d) and enter the result in the total refund box at the top of the schedule.” The same total goes on Form 8849, line 1a. The claim has a floor: “The amount claimed on Schedule 1 must be at least $750.” You may reach it by adding quarters of your income tax year that no other claim has covered. |
| S1-Caution | Caution above line 1 | Signing the claim confirms the printed statement: “Claimant has the name and address of the person who sold the fuel to the claimant and the dates of purchase.” Keep the fuel invoices; they are not attached. |
| S1-Period | Period of claim (From, To) | Month, day and year in MMDDYYYY format. “The claim must be filed during the first quarter following the last quarter included in the claim.” “Only one claim may be filed for a quarter.” Example: a claim for July to December 2026 is filed from January 1 to March 31, 2027. |
| 1a | Line 1a: Gasoline (nontaxable use) | “For line 1a, the gasoline must have been used during the period of claim for type of use 2, 4, 5, 7, 11, 12, 13, 14, or 15.” For a carrier the one that matters is type of use 2, which the Form 8849 instructions define as “Off-highway business use (for business use other than in a highway vehicle registered or required to be registered for highway use)”. Enter the type of use number in column (a), gallons in column (c), and rate times gallons in column (d). The rate printed on the May 2020 schedule is $.183; CRN 362. |
| 3-dye | Line 3 certification and exception | By claiming on line 3 you certify: “Claimant certifies that the diesel fuel did not contain visible evidence of dye.” If some did, attach a detailed explanation and check the box. Dyed diesel carries only the small LUST tax (Pub. 510), so it has nothing to refund on this line; see dyed diesel. |
| 3a | Line 3a: Nontaxable use of undyed diesel | “For line 3a, the diesel fuel must have been used during the period of claim for type of use 2, 6, 7, 8, 11, 12, 13, 14, or 15.” For a motor carrier that is mostly type of use 2. Pub. 510 says “Off-highway business use includes fuel used in a separate motor to operate special equipment, such as a refrigeration unit, pump, generator, or mixing unit.” The rate printed is $.243 a gallon; CRN 360. Line 3b (farm use) shares the column (d) amount with 3a. |
Lines a carrier does not use
These lines serve other businesses. They have no boxes on the image above.
| Lines | What they cover | Who uses them |
|---|---|---|
| 1b, 2a to 2d | Exported gasoline; aviation gasoline | Exporters, aircraft operators |
| 3b to 3e | Undyed diesel on a farm, in trains, in certain buses, exported | Farms, railroads, bus operators, exporters |
| 4a to 4f, 5a to 5e | Undyed kerosene and kerosene used in aviation | Heating, boats, aviation |
| 6 and 7 | Alternative fuel; diesel-water fuel emulsion | Users of taxed alternative fuels and emulsions |
| 8a and 8b | Exported dyed fuels and gasoline blendstocks | Exporters |
Form 8849 page 1
Schedule 1 rides on Form 8849, Claim for Refund of Excise Taxes (Rev. May 2026). The Form 8849 Schedule 6 page shows page 1 of Form 8849 with every box marked; for a Schedule 1 claim the only differences are the box you check and the total on line 1a.
| Form 8849 box | For a Schedule 1 claim |
|---|---|
| Name, EIN, address, ZIP, month the tax year ends | As on your income tax return; the same name and EIN go on Schedule 1. |
| Schedules attached | Check the Schedule 1 box. “Only attach the schedules on which you are claiming a refund.” |
| Line 1a, total refund | The Schedule 1 total refund (plus any other schedule you attach). |
| Sign Here and paid preparer | Signed by a person with authority to sign for the claimant; a paid preparer who is not your employee signs too. |
One wrinkle: the May 2020 schedule prints “Don’t file with any other schedule.” The May 2026 Form 8849 instructions name only three schedules that must go alone: “Schedules 2, 5, and 8 cannot be filed with any other schedules on Form 8849.” Filing Schedule 1 on its own Form 8849 satisfies both.
Schedule 1 during the year, or Form 4136 once a year
Schedule 1 is the periodic route. If you missed it or did not reach $750, the yearly route is the income tax credit on Form 4136. The Form 8849 instructions put it this way: “If a claim was not made for any gallons during the income tax year on Form 8849, an annual claim may be made.” The same gallons cannot be claimed twice.
| Schedule 1 (Form 8849) | Form 4136 | |
|---|---|---|
| When | Quarterly, in the quarter after the claim period | Once a year, with the income tax return |
| Minimum | $750 per claim | Annual claim; the $750 floor is a Schedule 1 rule |
| Carrier lines | 1a (gasoline), 3a (undyed diesel) | 1a and 3a, plus Part I business information |
| Result | A refund | A credit against income tax |
Refunds of excise tax you deducted are income. “Include any refund of excise taxes in your gross income if you claimed the amount of the tax as an expense deduction that reduced your income tax liability.”
State fuel tax is a separate claim
Schedule 1 returns only the federal tax. Reefer fuel bought at the pump also carried state fuel tax, and the IFTA return does not refund it: “Licensees must submit claims for refund for tax paid on tax-exempt fuel directly to the respective jurisdiction.” See the tax-paid fuel credits guide for what counts on the IFTA return.
How it connects
- Which fuel qualifies and which form to use: reefer and off-highway fuel tax refunds.
- The tax being refunded: federal diesel and gasoline excise tax rates.
- The yearly alternative: the Form 4136 form page. Refunds of Form 2290 tax: Form 8849 Schedule 6.
- Keeping the proof: what a fuel receipt must show.
Questions filers ask
Can I claim the fuel my truck burns to run a PTO?
No. Pub. 510 says off-highway business use does not include fuel used in the propulsion motor of a registered highway vehicle, even when that motor runs equipment through a power take-off.
Which line is reefer fuel?
Undyed diesel burned in a refrigeration unit with its own motor is off-highway business use: line 3a, type of use 2, at the $.243 rate printed on the schedule, CRN 360.
My reefer fuel for the quarter was only $400 of tax. Can I file?
Not on Schedule 1 alone. The claim must be at least $750; you can add quarters of the same income tax year that no other claim covered, or take the whole year on Form 4136.
When is the claim due?
During the first quarter after the last quarter in the claim. Fuel used July through December 2026 is claimed between January 1 and March 31, 2027.
Do I send receipts with Schedule 1?
No. You confirm that you have the seller's name and address and the purchase dates. Keep the invoices with your records in case the IRS asks.